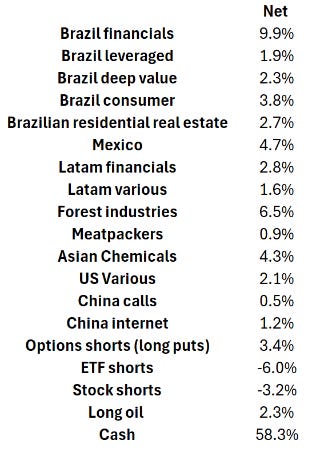
After every quarter, I provide a review of the performance and positions of my two personal accounts (IBKR and Argentina, Argentina having been discontinued since 2Q26). I think this provides readers with more context and transparency about the way I think and act as an investor myself. Most of the names for which I have positions have been covered in the blog. This article reviews 3Q26.
You can visit previous reviews in the Index

The article posts the historical returns, 3Q26 returns, sources of the quarterly returns, the changes in positions during the quarter, and finally, the ending positioning.
Before beginning, I wanted to thank all of Quipus Capital’s readers for your support, especially those who have upgraded monthly or yearly. The blog has more than 2,500 readers. Writing and researching for Quipus is a great pleasure.
Disclaimer: The opinions expressed in the Blog are for general informational purposes only and are not intended to provide specific advice or recommendations for any individual or on any specific security or investment product.
IBKR account 3Q26
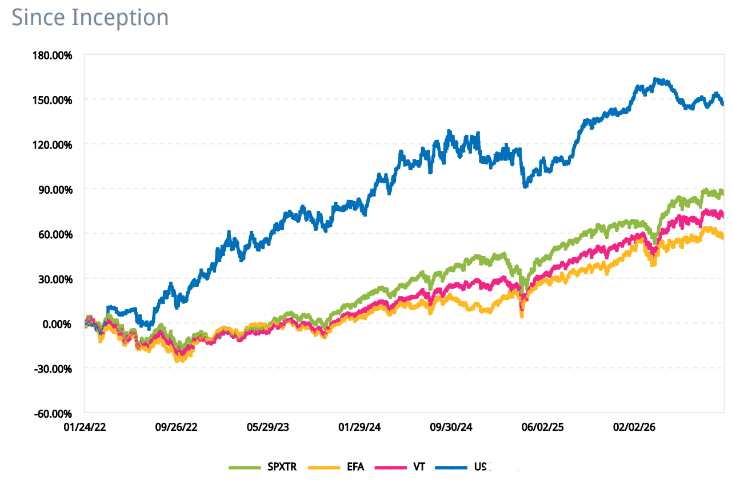
Q3: 1.27%%; YTD: 2.73%; 1 Year: 5.68%; Since inception (Jan22): 147.72% (CAGR 21%)
Historical returns
The first image below shows the performance of the account by month and quarter (“U91..” column) compared to three benchmarks (SPXTR, EFA, and VT). The second image shows the same comparison in chart form, ending in 2Q26.
Return sources for the quarter and changes in positions
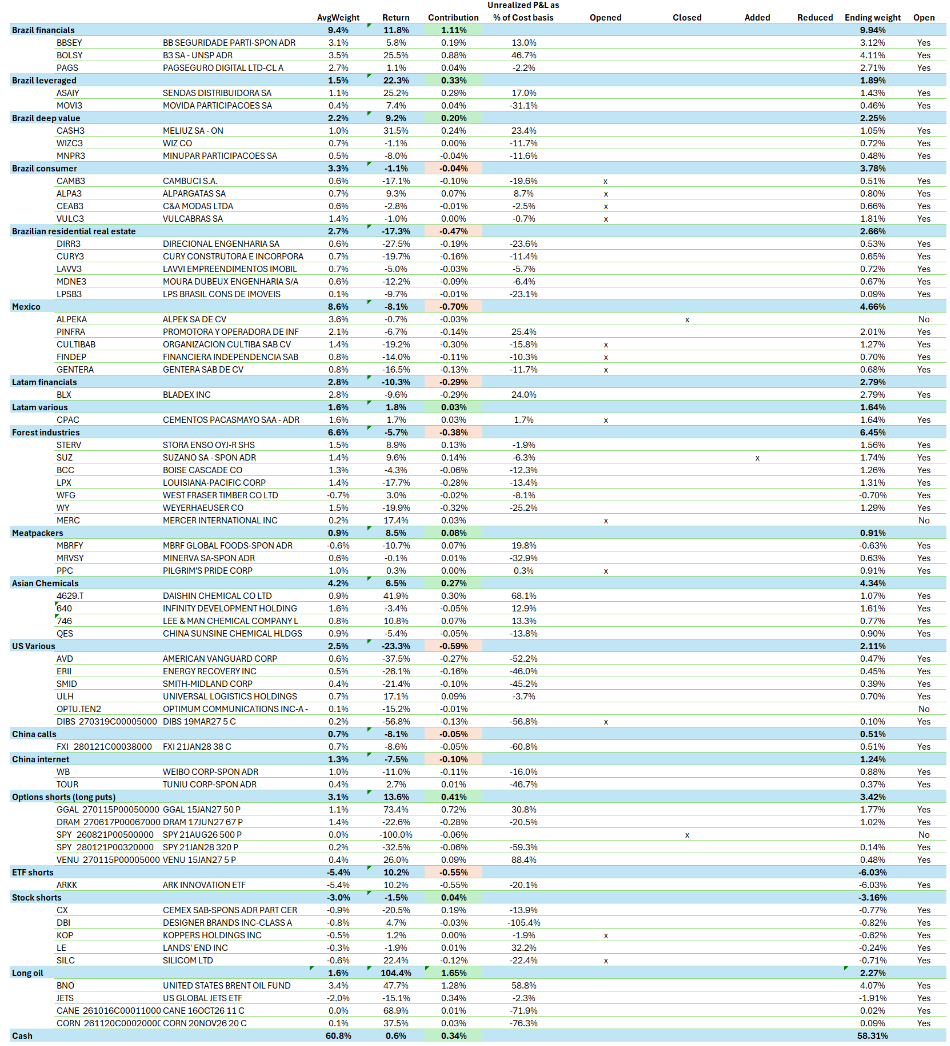
This quarter has been rather uneventful, as reflected in the 1.27% return. Nothing much has happened, neither positive nor negative.
Brazil
The Brazilian names more or less all performed positively, especially the leveraged names, given that Brazil’s rates are decreasing. The residential real estate names are the only ones down in my Brazilian portfolio. I think the reason is that these names are a little more Lula-exposed, and overall Brazil has performed well because Lula is expected to lose the elections (or his chances have thinned versus previous periods).
I added a couple of Brazilian consumer names that I had studied during the quarter.
In case you want to check the Brazilian names in the list, here are the more relevant articles.


Mexico
I added three positions in Mexico, which I have not had time to write about, but are going to be topics of new posts this quarter. These are primarily names that have screened cheap either on a balance sheet or earnings basis.
I also finished closing my long-standing Alpek position.
Forest Industries
The Forest Industries positions did not do very well, in particular Weyerhaeuser and Louisiana-Pacific. These names are very negatively correlated with rates, in particular Weyerhaeuser, because they damage construction activity and, therefore, demand for wood. Weyerhaeuser, being almost a kind of bond in some way, is even more hit by interest rates.
I did add to Suzano on the basis that global disruptions to trade are beneficial to industries exposed to Chinese oversupply.


Meatpackers
I bought PPC in early August as the company went down because of a bad cycle in poultry (which tends to be short-lived). The name went up a bunch on the announcement that JBS (owner of 80%) wanted to acquire the remaining 20% stake of the company and delist it. The problem is that because the deal is share-for-share, now the stock trades following JBS, which has gone down. I think JBS is not a terrible value at these prices, so I’m waiting.

US various
I got badly hit with AVD (the company is hemorrhaging cash and probably is going bankrupt unless the fertilizer market turns rapidly) and with ERII (the company cancelled its CO2 refrigeration pressure exchanger project and the war in Iran is very bad for their mostly MENA water clients).
Oil
The BNO long and JETS short pair of long-oil is the best contributor. I keep believing that the oil disruptions from the war are far from over.
Ending positions